Getting approved for your first credit card can feel like a catch-22. Many lenders want to see a credit history before issuing a credit card, but how can you build credit if no one approves you in the first place?
The good news is that having no credit history does not mean you cannot get a credit card. Financial institutions understand that everyone starts somewhere, which is why several credit-building products are specifically designed for beginners.
Whether you’re a student, recent graduate, young professional, or someone who has never borrowed money before, there are practical ways to obtain your first credit card and start building a strong financial foundation.
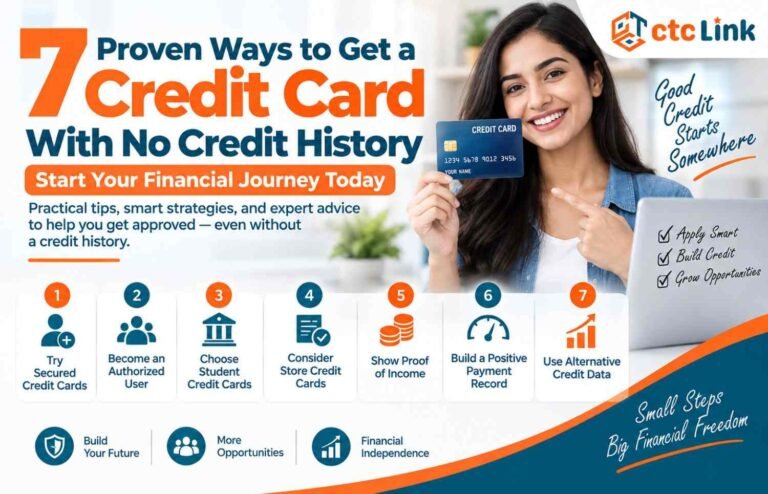
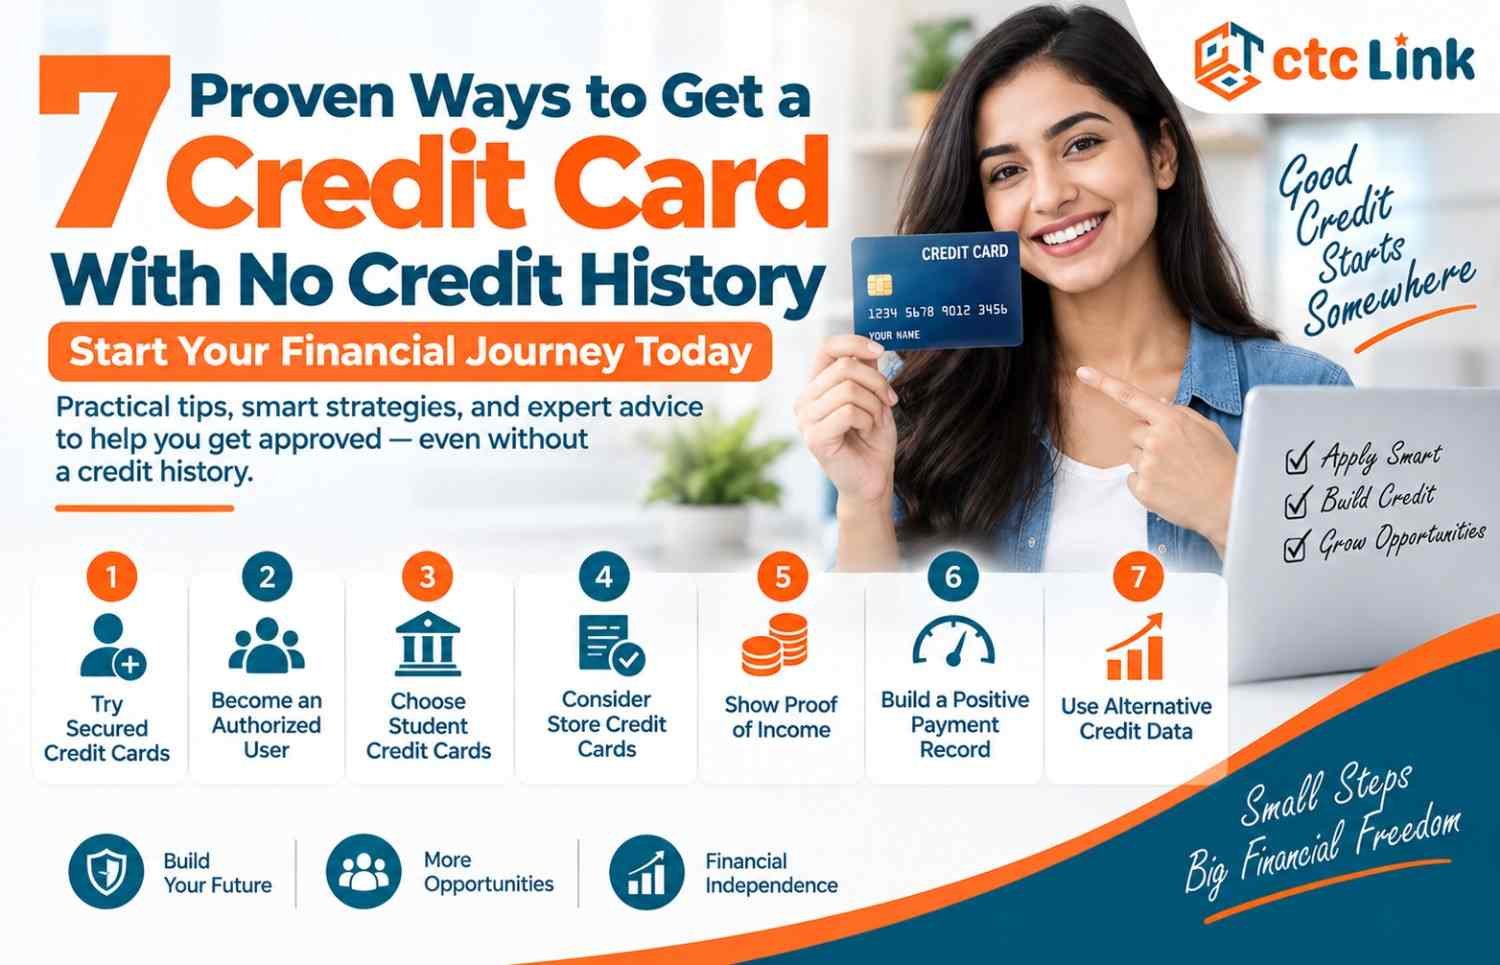
In this guide, we’ll explore 7 proven ways to get a credit card with no credit history, along with expert tips to improve your approval chances and build credit responsibly.
Why Is It Difficult to Get a Credit Card With No Credit History?
Before discussing solutions, it’s important to understand why lenders hesitate to approve applicants with no credit history.
When you apply for a credit card, issuers evaluate your financial reliability. They typically review:
- Credit score
- Payment history
- Existing debts
- Length of credit history
- Income stability
Without a credit history, lenders have limited information about your borrowing habits. This uncertainty increases perceived risk.
However, many banks offer alternative products that help first-time borrowers establish credit.
1. Apply for a Secured Credit Card
A secured credit card is often the easiest and most effective way to get approved without a credit history.
Unlike traditional credit cards, secured cards require a refundable security deposit. The deposit typically becomes your credit limit.
Example:
- Security Deposit: $300
- Credit Limit: $300
Since the deposit reduces the lender’s risk, approval requirements are generally more flexible.
Benefits of Secured Credit Cards
- Easier approval process
- Reports to major credit bureaus
- Helps establish credit history
- Can lead to an unsecured card later
Many financial experts consider secured credit cards the best starting point for building credit from scratch.
2. Apply for a Student Credit Card
If you’re enrolled in a college or university, a student credit card may be one of your best options.
Student cards are designed specifically for individuals with little or no credit history.
Advantages of Student Credit Cards
- Easier approval requirements
- Low credit limits
- Cashback rewards
- Credit education tools
Many student cards also offer mobile apps and financial resources to help young adults manage money responsibly.
If you’re a student with some form of income, your approval chances may be significantly higher.
3. Become an Authorized User
One of the fastest ways to begin building credit is by becoming an authorized user on someone else’s credit card account.
A parent, spouse, or trusted family member can add you to their account without making you responsible for payments.
When the primary cardholder maintains:
- On-time payments
- Low balances
- Long account history
You may benefit from that positive credit activity appearing on your credit report.
Important Note
Only become an authorized user on an account with a strong payment history. Poor account management could negatively affect your credit-building efforts.
Also Read: Can You Get a Credit Card With No Credit? Everything You Need to Know
4. Choose a Credit Card Designed for Beginners
Many banks offer credit cards specifically created for people with limited or no credit history.
These cards often feature:
- Relaxed approval requirements
- Lower credit limits
- Minimal fees
- Credit-building opportunities
While these cards may not offer premium travel rewards or luxury benefits, they provide an excellent starting point for establishing credit.
Research issuers that specifically advertise cards for first-time credit users.
5. Use a Co-Signer (When Available)
Some lenders allow applicants to apply with a co-signer.
A co-signer agrees to take responsibility for the debt if the primary cardholder fails to make payments.
Because the lender can also evaluate the co-signer’s credit profile, approval chances may improve.
Benefits of a Co-Signer
- Increased approval odds
- Opportunity to build independent credit
- Potential access to better credit limits
Not all issuers allow co-signers, so check eligibility requirements before applying.
6. Open a Relationship With a Bank or Credit Union
Having an existing banking relationship can sometimes improve your chances of getting approved for a credit card.
If you already have:
- A checking account
- A savings account
- Regular direct deposits
The financial institution may view you as a lower-risk customer.
Why Credit Unions Can Be Helpful
Credit unions often focus on member relationships rather than solely relying on credit scores.
As a result, they may offer more flexible approval standards compared to large banks.
Many first-time borrowers find success applying through local credit unions.
7. Demonstrate Stable Income
Even if you don’t have a credit history, lenders still want to know whether you can repay borrowed money.
A stable income can strengthen your application significantly.
Acceptable income sources may include:
- Full-time employment
- Part-time jobs
- Freelance work
- Self-employment income
- Investment income
- Government benefits (where permitted)
The stronger your income profile, the more confidence lenders may have in your ability to manage credit responsibly.
How to Improve Your Approval Chances
Beyond choosing the right credit card, there are several steps you can take to increase your likelihood of approval.
Apply for One Card at a Time
Submitting multiple applications within a short period can create red flags for lenders.
Instead:
- Research carefully
- Compare requirements
- Apply selectively
Quality matters more than quantity.
Verify Your Information
Ensure all details on your application are accurate, including:
- Name
- Address
- Employment information
- Income details
Mistakes can delay or even result in application denials.
Start With Realistic Expectations
Many beginners apply for premium rewards cards with strict approval requirements.
Focus first on establishing credit. Better cards can come later.
What Happens After You’re Approved?
Getting approved for a credit card is only the beginning. Building good credit requires responsible usage.
Make Payments on Time
Your payment history plays a major role in your future credit score.
Late payments can significantly impact your ability to qualify for loans and credit products later.
Keep Credit Utilization Low
Experts generally recommend using less than 30% of your available credit limit.
Example:
- Credit Limit: $1,000
- Ideal Balance: Below $300
Lower utilization demonstrates responsible credit management.
Use the Card Regularly
Small recurring purchases such as:
- Mobile bills
- Streaming subscriptions
- Fuel purchases
- Grocery expenses
can help establish consistent account activity.
Avoid Carrying Excessive Debt
Credit cards should be used as a financial tool—not as a source of long-term borrowing.
Whenever possible, pay your balance in full each month.
Common Mistakes to Avoid
Missing Payments
Late payments can damage your developing credit profile.
Maxing Out Your Card
Using your entire credit limit may hurt your credit score.
Applying for Too Many Cards
Multiple credit inquiries within a short period can reduce approval chances.
Ignoring Statements
Regularly reviewing your statements helps identify errors and track spending.
Spending Beyond Your Budget
Only charge purchases you can comfortably afford to repay.
How Long Does It Take to Build Credit?
Building credit is a gradual process.
Most people begin establishing a credit profile within a few months of responsible credit usage.
Factors influencing credit growth include:
- Consistent payments
- Credit utilization
- Account age
- Number of credit accounts
Patience and consistency are key to achieving a strong credit score.
Benefits of Building Credit Early
A positive credit history can open the door to numerous financial opportunities.
Good credit may help you:
- Qualify for premium credit cards
- Receive lower interest rates
- Obtain personal loans
- Secure mortgage financing
- Rent apartments more easily
- Access higher credit limits
Building credit early can provide long-term financial advantages.
Final Thoughts
Getting a credit card with no credit history may seem challenging, but it is entirely possible when you choose the right approach. Secured credit cards, student credit cards, authorized user status, and beginner-friendly credit products can all help you enter the world of credit successfully.
The most important step is using your card responsibly after approval. By paying bills on time, maintaining low balances, and avoiding unnecessary debt, you can gradually build a strong credit profile that supports your future financial goals.
Remember, everyone starts with no credit at some point. With the right strategy and consistent financial habits, you can establish excellent credit and unlock better borrowing opportunities in the years ahead.
Frequently Asked Questions (FAQs)
1. Can I get a credit card with absolutely no credit history?
Yes. Secured credit cards, student credit cards, and beginner credit cards are specifically designed for people with no credit history.
2. What is the easiest credit card to get with no credit?
Secured credit cards are generally considered the easiest option because they require a refundable security deposit.
3. Will a credit card help me build credit?
Yes. Responsible credit card use, including on-time payments and low balances, helps establish and improve your credit history.
4. How much credit history do I need to get a regular credit card?
Requirements vary by issuer, but many traditional credit cards require at least some established credit history and a fair credit score.
5. How long does it take to build credit from scratch?
Many individuals begin generating a credit score within a few months of consistent, responsible credit usage.
About the Author